
Last Updated: October 23, 2026
Quick Summary
Whether to file a homeowners insurance claim depends on comparing your repair costs against your deductible and potential rate increases over three to five years. Filing makes financial sense when the insurer's payment significantly exceeds the combined cost of your deductible and anticipated premium increases.
- Contact your insurer before filing to estimate how a claim might affect your rates without formally filing.
- A single claim typically stays on your record for three to five years and may affect renewal decisions and rates.
- Calculate the true net benefit by subtracting your deductible and estimated long-term rate increases from the insurer's payment.
- Storm and weather-related claims generally have less impact on your insurability than claims for damage you caused or failed to prevent.
- Most policies require prompt notice of damage within 30 to 60 days, so notify your insurer even if you're still deciding whether to formally file.
Table of Contents
- When Filing a Homeowners Insurance Claim Makes Financial Sense
- Understanding Your Home Insurance Claim Deductible
- Will Filing a Homeowners Insurance Claim Raise My Rates?
- The Homeowners Insurance Claim Process: Step by Step
- Homeowners Insurance Claim Examples: Common Scenarios
- Break-Even Analysis: Repair Costs vs. Deductible and Premium Impact
- What to Do Before Filing: Contact Your Insurer First
- If Your Claim Is Denied or Underpaid
- Frequently Asked Questions
When Filing a Homeowners Insurance Claim Makes Financial Sense
Whether to file a homeowners insurance claim depends on comparing your repair costs against your deductible and the potential impact on your future premiums.
Start by getting repair estimates. That small recovery may not justify the claim filing.
The real question: Will filing a homeowners insurance claim cost you more in the long run through rate increases than you save by having the insurer pay?
Consider filing when repair costs significantly exceed your deductible.
Understanding Your Home Insurance Claim Deductible
Your deductible is the amount you pay out of pocket before your homeowners insurance claim coverage kicks in. Common deductibles range from $500 to $2,500, though some policies offer higher deductibles in exchange for lower premiums.
How the Deductible Affects Your Out-of-Pocket Costs
The deductible reduces the claim amount dollar-for-dollar. If your home suffers $8,000 in damage and your deductible is $1,000, your insurer pays $7,000 and you pay $1,000.
Some policies include separate deductibles for specific perils. Storm damage, for instance, may have a higher deductible than fire damage. Wind or hail damage often carries a separate deductible, sometimes a percentage of your home's insured value rather than a flat dollar amount.
Understanding what your specific deductible covers is essential before filing. Review your policy documents or call your agent to confirm:
- Your standard deductible amount
- Whether specific perils have different deductibles
- If a percentage-based deductible applies to certain damage types
- How the deductible applies to additional living expenses if you're displaced
Will Filing a Homeowners Insurance Claim Raise My Rates?
Filing a homeowners insurance claim can affect your rates, though the impact varies. Some insurers offer protections that prevent rate increases after a single claim, while others may raise rates regardless.
The key variable is whether your insurer has claim forgiveness or claim rate protection programs. Kaiser Agency partners with Allstate, which offers Claim RateGuard®, a feature that prevents your premium from increasing just because you file a claim. This type of protection can make filing a claim far more attractive financially.
Without such protection, expect potential rate increases after filing. The increase typically ranges from modest to substantial, depending on:
- Your claims history
- The type of damage (weather-related claims often have less impact than at-fault damage)
- Your insurer's underwriting practices
- Your location and risk profile
How Claim History Influences Renewal and Insurability
A single claim stays on your record for three to five years. During that period, it may affect renewal decisions and rates at your current insurer and future insurers if you switch.
Multiple claims within a short timeframe can trigger non-renewal, meaning your insurer declines to renew your policy.
Claims for weather-related damage (storms, hail, wind) generally have less impact on your insurability than claims for damage you caused or failed to prevent.
The Homeowners Insurance Claim Process: Step by Step
Filing a homeowners insurance claim follows a predictable sequence.
Step 1: Contact Your Insurer Promptly
Call your insurer as soon as damage occurs.
When you call, have ready:
- Your policy number
- Date and time the damage occurred
- Description of what happened
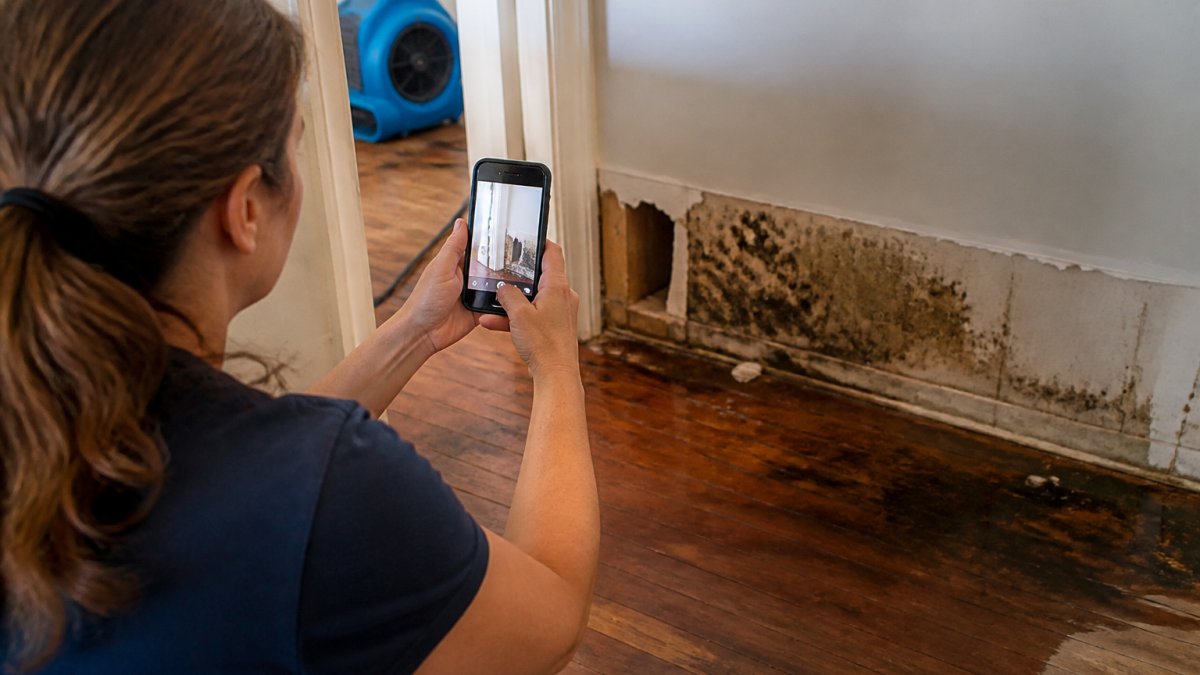
- Photos or video if safe to take them
Step 2: Mitigate Further Damage
Your policy requires you to take reasonable steps to prevent additional damage.
Failure to mitigate can reduce your claim payout. Document these efforts with photos.
Step 3: File Your Formal Claim
Your insurer will send claim forms or provide them online. Complete these thoroughly and honestly. Include:
- Detailed description of the damage
- Date it occurred
- Cause of damage
- List of damaged items with approximate values
- Photos and videos
- Repair estimates from contractors
Step 4: Meet the Insurance Adjuster
The insurer assigns an adjuster to inspect the damage. Schedule this inspection promptly.
Bring your documentation, photos, receipts, repair estimates, and proof of loss.
Step 5: Review the Settlement Offer
The insurer sends a settlement offer based on the adjuster's report.
Documentation and Damage Assessment
Strong documentation is your best defense in a claim dispute. Photograph or video everything:
- Overall view of damaged areas
- Close-ups of specific damage
- Before photos if you have them
- Surrounding context (location in the home, neighboring items)
Collect receipts for repairs and replacement items. If you don't have original receipts, gather estimates from contractors showing what replacement costs.
For valuable items, provide proof of ownership. Jewelry, electronics, and artwork may require appraisals or purchase documentation.
Prompt Notice Requirements and Filing Deadlines
Most policies require notice within 30 to 60 days of damage. Some states impose stricter timelines. Don't delay, prompt notice protects your claim.
Filing deadlines vary by state and policy. Some allow up to one year from the loss; others require filing within 90 days. Check your policy or ask your agent for your specific deadline.
Send us a referral for a Home and Auto Quote →
Missing deadlines can result in claim denial, so mark your calendar and file promptly.
Homeowners Insurance Claim Examples: Common Scenarios
Real-world examples show how different damage types affect claim decisions.
Storm and Water Damage Claims
A hailstorm damages your roof, requiring $12,000 in repairs. Your deductible is $1,000. The insurer pays $11,000; you pay $1,000 out of pocket.
This claim is clearly worth filing. The insurer's payment far exceeds your deductible.
A pipe bursts in your basement during freezing weather, causing $6,500 in water damage. Your deductible is $2,500. The insurer would pay $4,000.
Again, filing makes sense. The payout significantly exceeds the deductible.
Fire and Theft Claims
Your home catches fire, destroying the kitchen and damaging adjacent rooms. Total loss is $45,000. Your deductible is $1,000.
File immediately. This is a major loss where the insurer's payment vastly exceeds your deductible.
A burglar steals electronics and jewelry worth $3,200. Your deductible is $1,000. The insurer pays $2,200.
Filing is worthwhile. Theft claims typically have less impact on rates than weather or fire claims, as they don't suggest a systemic risk with your property.
Exclusions and What Is Not Covered
Homeowners insurance does not cover all damage. Common exclusions include:
- Wear and tear: Gradual deterioration from age or lack of maintenance
- Maintenance failures: Damage from neglected repairs (burst pipes from uninsulated lines, roof leaks from missing shingles)
- Flood damage: Requires a separate flood insurance policy
- Earthquake damage: Requires a separate earthquake endorsement
- Mold: Often excluded unless caused by a covered peril like a sudden pipe burst
If damage falls under an exclusion, filing a claim wastes time and may harm your relationship with your insurer. Before filing, confirm that the damage type is actually covered.
Break-Even Analysis: Repair Costs vs. Deductible and Premium Impact
Deciding whether to file requires weighing immediate savings against long-term costs.
Calculating Long-Term Costs
Here's a practical framework:
Immediate calculation:
- Repair cost: $X
- Your deductible: $Y
- Insurer's payment: $X minus $Y
- Your out-of-pocket: $Y
Long-term calculation:
- Estimated annual rate increase: $Z per year
- Years the claim affects rates: typically 3-5 years
- Total long-term cost from rate increases: $Z × years
- True net benefit: (Insurer's payment) minus (Deductible) minus (Total long-term rate increases)
Example:
- Roof damage repair cost: $10,000
- Your deductible: $1,500
- Insurer pays: $8,500
- Your immediate cost: $1,500
- Estimated annual rate increase: $200/year for 5 years = $1,000 total
- True net benefit: $8,500 minus $1,500 minus $1,000 = $6,000
In this scenario, filing makes strong financial sense.
Another example:
- Bathroom damage repair cost: $4,000
- Your deductible: $2,500
- Insurer pays: $1,500
- Your immediate cost: $2,500
- Estimated annual rate increase: $150/year for 3 years = $450 total
- True net benefit: $1,500 minus $2,500 minus $450 = negative $1,450
Here, paying out of pocket costs less than filing and absorbing future rate increases.
| Scenario | Repair Cost | Deductible | Insurer Pays | Out-of-Pocket | Est. Rate Increase | Net Benefit |
|---|---|---|---|---|---|---|
| Major damage | $15,000 | $1,000 | $14,000 | $1,000 | $800/5 years | +$12,200 |
| Moderate damage | $6,000 | $2,500 | $3,500 | $2,500 | $400/3 years | +$600 |
| Minor damage | $3,000 | $1,500 | $1,500 | $1,500 | $200/3 years | -$200 |
What to Do Before Filing: Contact Your Insurer First
Before formally filing a homeowners insurance claim, call your agent or insurer for a preliminary conversation. Many insurers offer this guidance at no cost and without triggering a formal claim.
Ask your insurer:
- Will this type of damage be covered?
- What deductible applies?
- How might this claim affect my rates?
- What documentation do you need?
- What's the timeline for inspection and settlement?
This conversation gives you the information to decide whether filing makes financial sense. If you decide to proceed, you're already prepared with the details.
Some homeowners worry that calling to ask questions triggers a claim. It doesn't. A claim is formal, you file it in writing or through your insurer's online system.
If Your Claim Is Denied or Underpaid
If your insurer denies your claim or offers a settlement you believe is unfair, you have options.
Gather additional documentation. If the denial cites insufficient proof, provide more.
Request a second inspection. You can hire an independent adjuster or engineer to assess the damage.
File a complaint. If you believe the insurer acted unfairly, file a complaint with your state's insurance commissioner.
Consider mediation or arbitration. Many policies include dispute-resolution clauses. Before litigation, explore these less costly options.
Filing a homeowners insurance claim is a financial decision, not an automatic one. Reach out for a policy review and claim guidance tailored to your situation.
Frequently Asked Questions
Should I file a homeowners insurance claim if the damage is less than my deductible?
No. If repair costs fall below your deductible, you'll pay the full amount out of pocket anyway, and filing a claim could increase your premiums or affect your claim history. For example, if your deductible is $1,000 and repairs cost $800, filing gains you nothing. Always compare repair costs to your deductible before contacting your insurer.
How much damage should I have before filing a homeowners insurance claim?
File a claim when repair costs exceed your deductible by a meaningful margin, typically $500 or more above it. This ensures the insurance payout justifies any potential premium increase. However, consider your insurer's specific claim history policies and whether you have Claim RateGuard or similar protection that prevents rate increases after a claim.
Will filing a homeowners insurance claim raise my premium?
Filing a claim may increase your premium at renewal, depending on your insurer, the type of claim, and your state's regulations. Some insurers offer protection against rate increases for your first claim. Your claim also becomes part of your claim history, which can affect future coverage options and insurability. Ask your agent about available protections before filing.
What types of damage are not covered by homeowners insurance?
Common exclusions include wear and tear, maintenance issues, flood damage, earthquakes, and mold damage (unless caused by a covered peril like sudden water damage). Damage from poor maintenance or gradual deterioration is not covered. Review your policy exclusions and consider separate flood or earthquake coverage if you live in a high-risk area.
What should I do immediately after discovering property damage?
First, prevent further damage by taking reasonable steps like turning off water or boarding up broken windows. Document the damage with photos and videos before cleanup. Then contact your insurer promptly to report the loss, most policies require notice within a specific timeframe. Keep receipts for any emergency repairs and gather proof of loss before the adjuster arrives.
